Originally published July 2024. Events, forecasts, and offers reflect this issue's publication date.
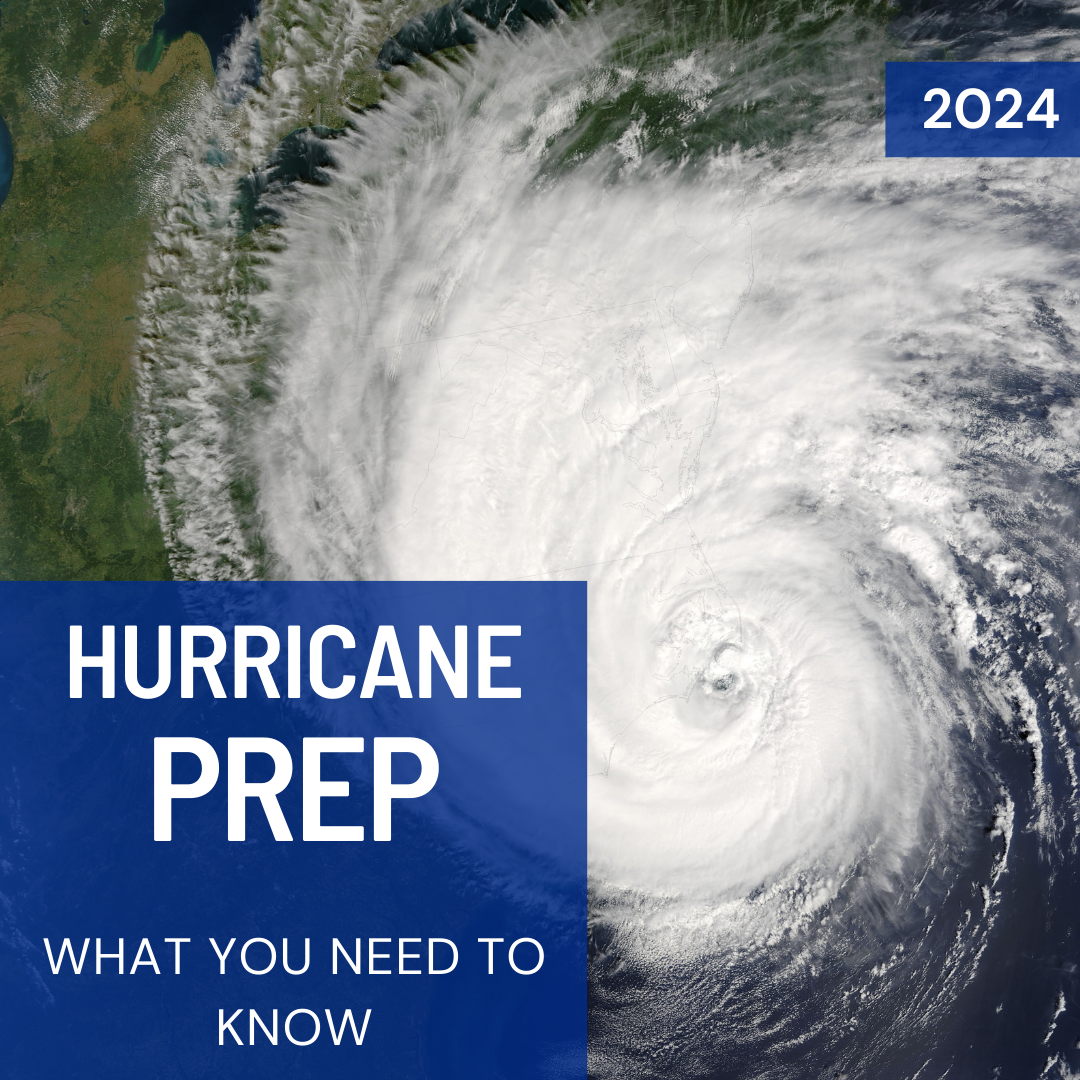
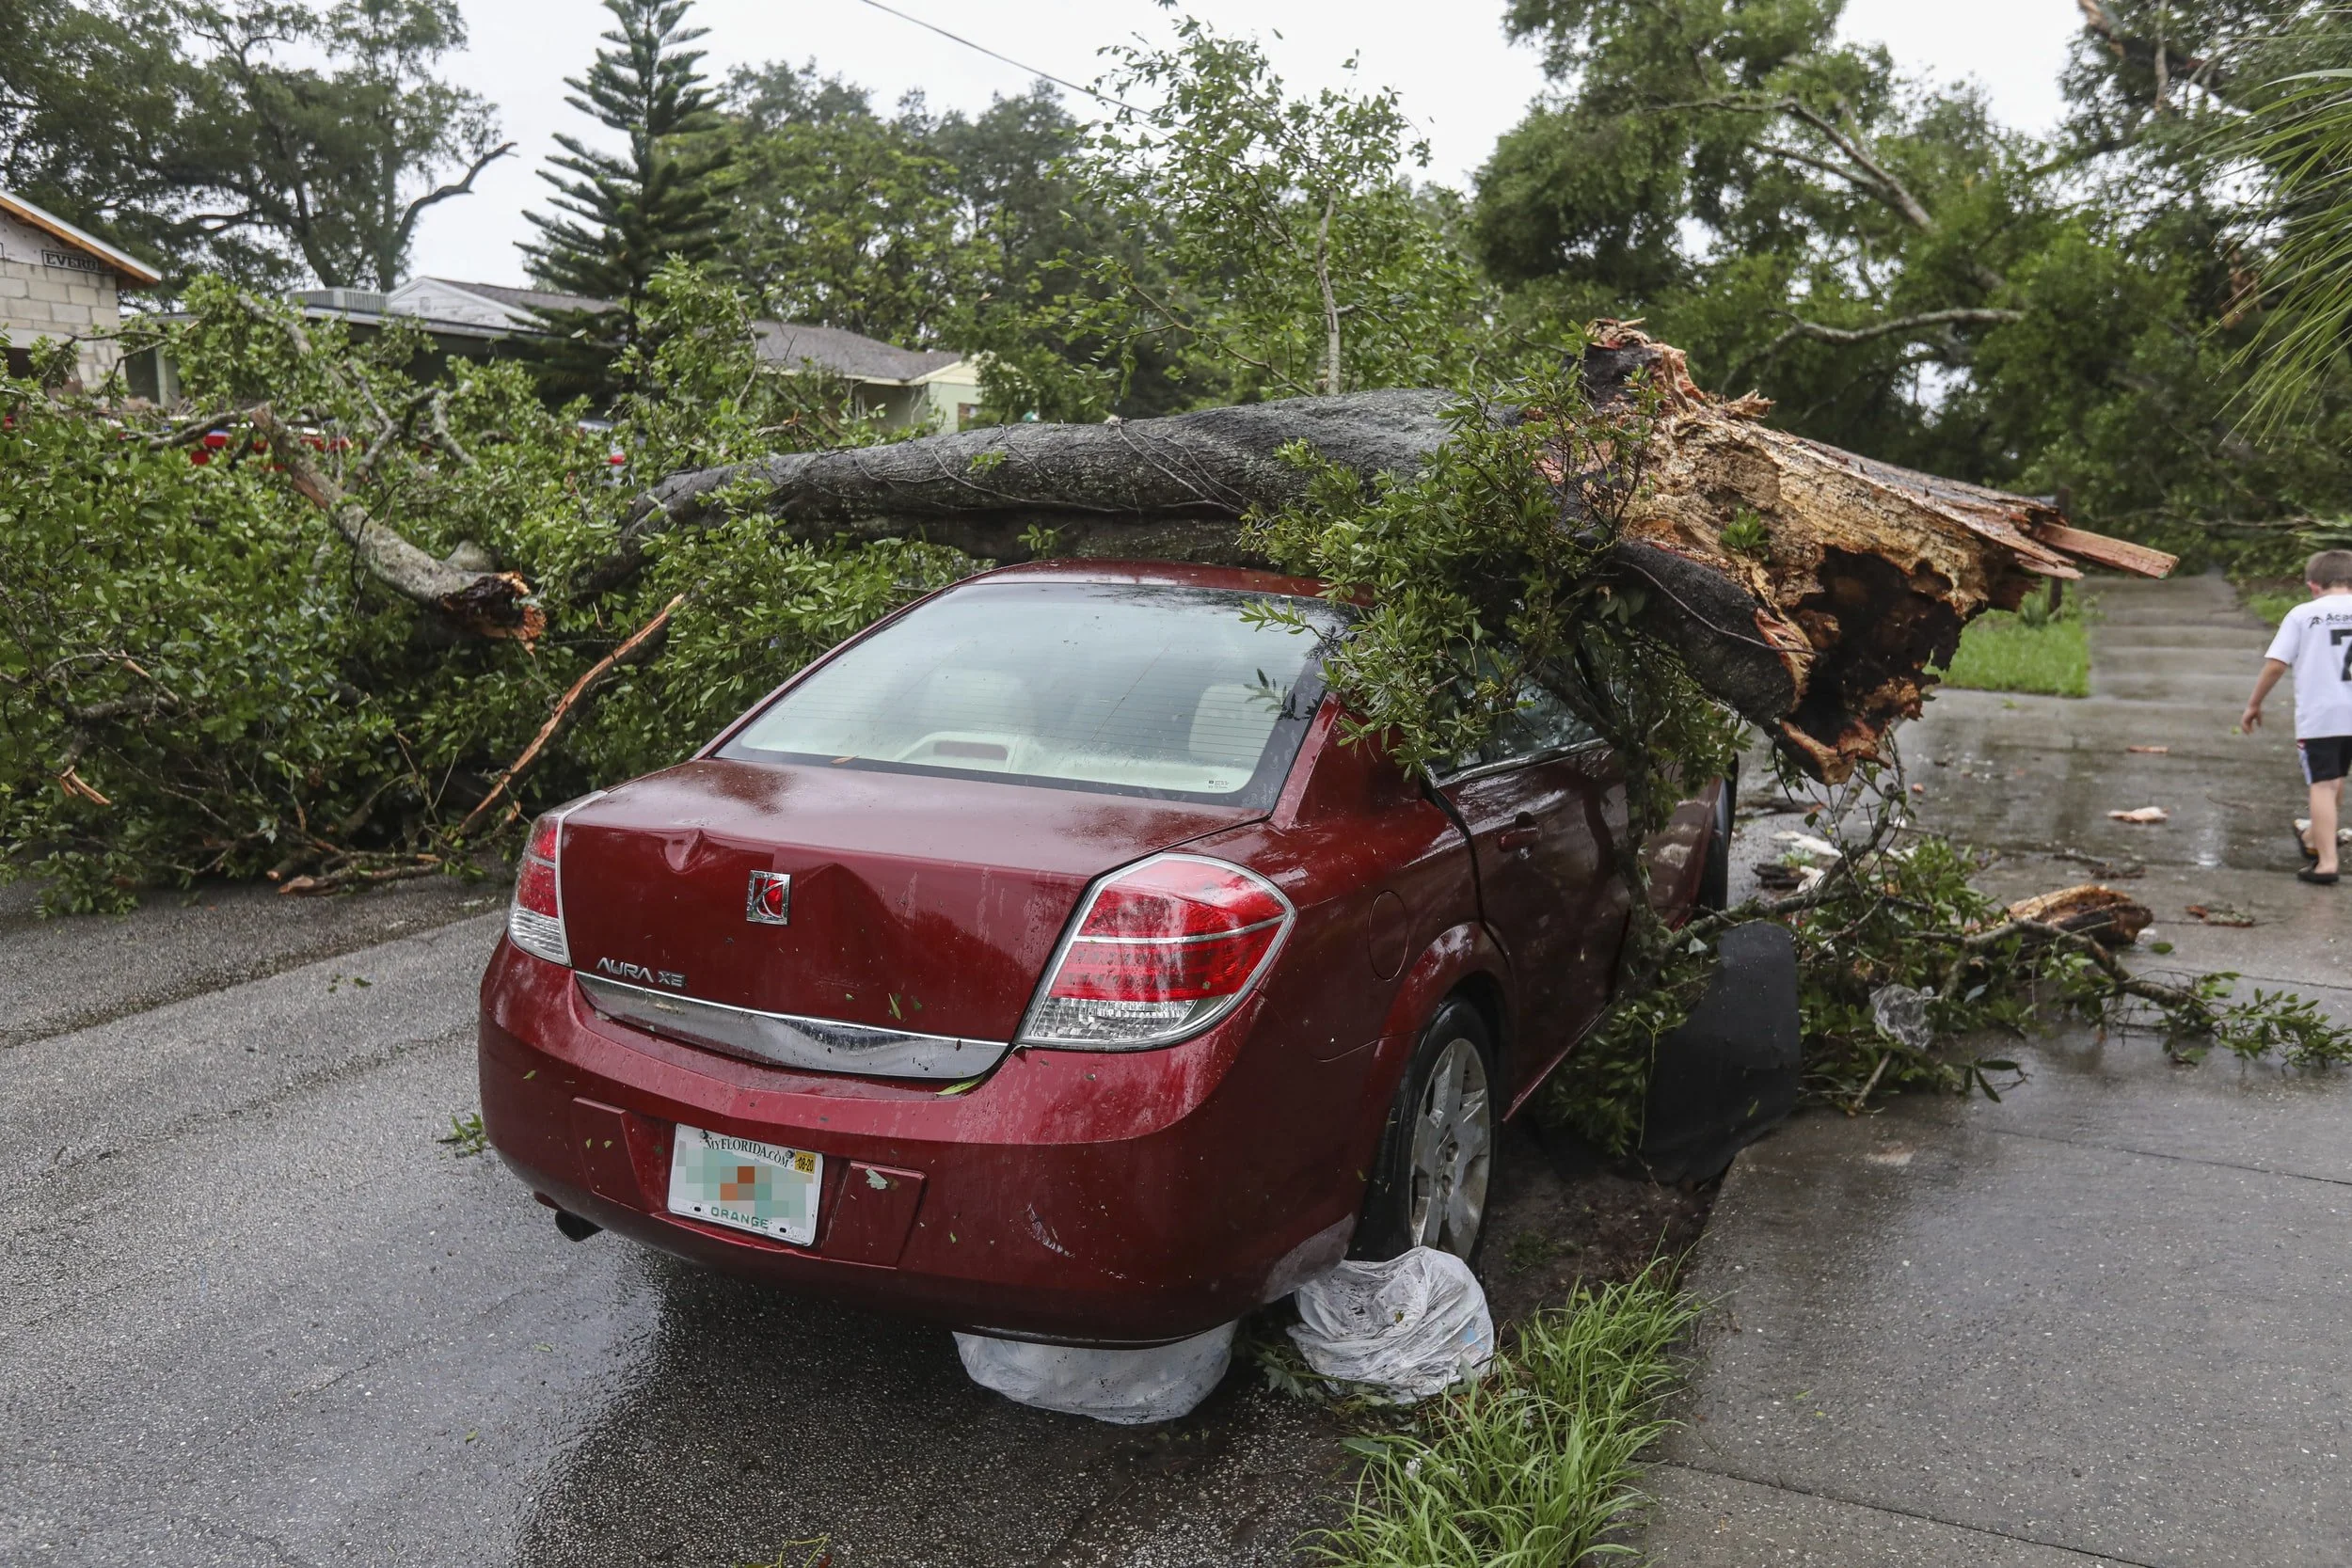
As we enter the peak of hurricane season, it’s crucial to be well-informed and prepared. In this month’s newsletter, we aim to highlight how Hillis Adjustment Agency can assist you in the aftermath of a storm, clarify important insurance policy clauses related to hurricanes, and address common pitfalls in hurricane damage claims.
Preparing for Peak Hurricane SeasonEssential Insights for Homeowners and Businesses
The Role of Your Hillis Public Adjuster During Hurricane Season
At Hillis Adjustment Agency, we understand the challenges that come with hurricane damage. Our team of expert public adjusters is here to help you navigate the claims process and secure the best possible settlement.
How Hillis Assists in the Aftermath of a Hurricane
Damage AssessmentWe conduct thorough inspections to document all damage, including hidden issues that might be overlooked.
Claim PreparationOur team prepares detailed and accurate estimate of the damages and also ensures all required documentation is included.
Negotiation with InsurersWe act as your advocate, negotiating with the insurance company to secure the best possible settlement.
Expert GuidanceWe provide advice on your rights and obligations under your insurance policy, helping you understand your coverage and exclusions.
The Benefits of Having Hillis Handle Claims
Maximized SettlementsOur Adjusters often secure the best possible settlements than policyholders might achieve on their own, thanks to their expertise.
Time SavingsWe handle the detailed work involved in filing and negotiating claims, saving you time and effort.
Stress ReductionBy managing the claims process, we allow you to focus on rebuilding your life and property.
Professional ExpertiseOur specialized knowledge of insurance policies and the claims process is invaluable in complex cases.
Insurance Policy Clauses Related to Hurricanes
Understanding your insurance policy is essential to ensure you have adequate coverage during hurricane season. Here are some key clauses and coverage details often overlooked:
Key Clauses and Coverage Details
DeductiblesMany policies have specific hurricane or windstorm deductibles, which are often higher than standard deductibles. Knowing your deductible can help you plan financially for potential out-of-pocket costs.
ExclusionsCommon exclusions in homeowner policies can include flood damage, mold, and other perils. It’s vital to read the fine print and understand what is and isn’t covered.
Additional Living Expenses (ALE)This coverage can help pay for temporary housing and related costs if your home becomes uninhabitable due to hurricane damage. Make sure you know the limits and conditions of ALE in your policy.
Differences Between Flood, Windstorm, and Hurricane Damage Coverage
Different types of damage require specific types of coverage:
Flood InsuranceStandard homeowner policies usually don’t cover flood damage. Separate flood insurance is necessary to cover storm surge and flooding.
Windstorm CoverageMay be included in standard policies but often comes with unique deductibles and exclusions. This coverage addresses damage caused by high winds.
Hurricane CoverageSometimes treated as a separate peril, with unique deductibles and policy conditions. This coverage typically includes both wind and rain damage caused directly by a hurricane.
Common Pitfalls in Hurricane Damage ClaimsDifferences Between Flood, Windstorm, and Hurricane Damage Coverage
Filing insurance claims can be complicated, and mistakes can lead to reduced payouts or denials. Here are some frequent mistakes and tips to avoid them:
Frequent Mistakes Homeowners and Businesses Make When Filing Claims
Inadequate DocumentationNot thoroughly documenting damage with photos, videos, and detailed descriptions can hurt your claim.
Delays in ReportingFailing to report damage promptly to your insurer can result in claim denial.
Incomplete or Incorrect FormsErrors in claim forms or missing information can delay the process or result in lower settlements.
Underestimating Repair CostsNot getting professional estimates can lead to undervalued claims.
Tips on How to Avoid These Pitfalls and Ensure a Smooth Claims Process
CALL HILLIS FIRST 1-800-HILLIS-1
Document EverythingTake comprehensive photos and videos of all damage and keep detailed records of communications with your insurer.
Report PromptlyNotify your insurance company of the damage as soon as possible to avoid delays in processing.
Get Multiple EstimatesObtain several repair estimates to support your claim with well-documented costs.
Hurricane Preparedness
- We are officially in Year 2 of our newsletter and we want to hear from you.
- What kinds of topics would you like us to cover in the coming months?
We value your feedback and would love to hear your suggestions for content that would be most helpful to you.
Images from the July 2024 issue